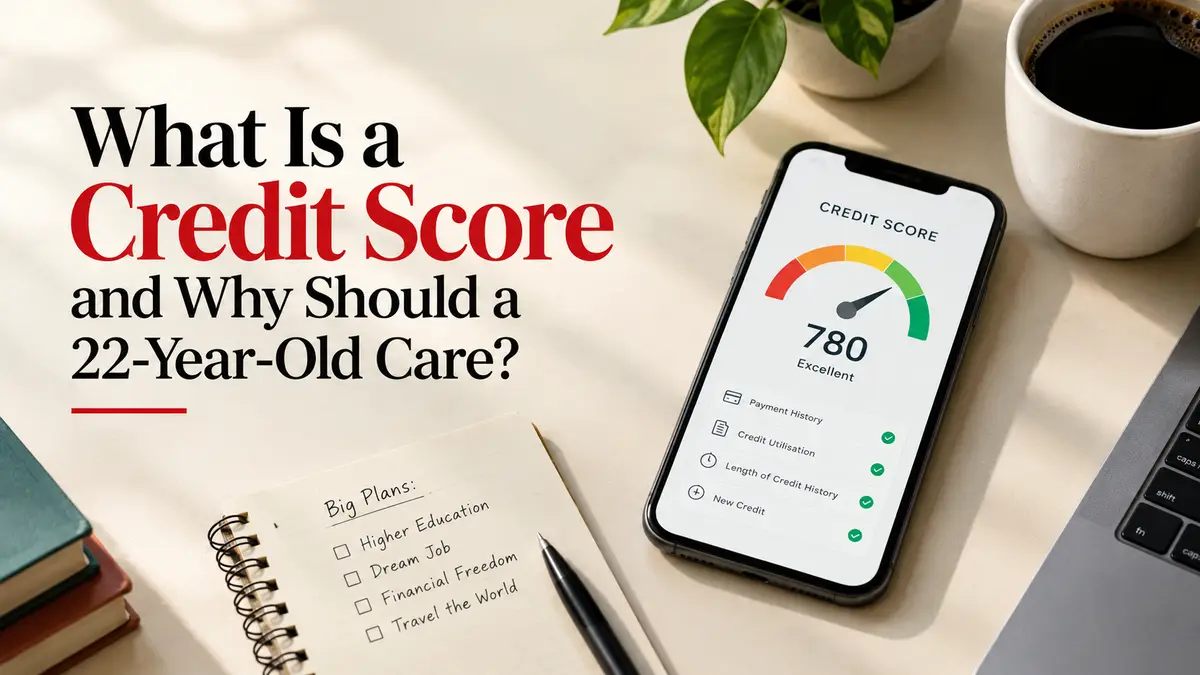
At 22, you are probably thinking about your first salary, paying rent, booking your next trip or figuring out how to make your money last until the end of the month. A three-digit number sitting somewhere in your financial records may not be high on that list; it probably should be. A credit score is one of those things that seems irrelevant until you suddenly need it. You may not care about your credit history when you are living with your parents, using a debit card and splitting restaurant bills with friends. But the moment you want a credit card, take an education loan, finance a car or eventually apply for a home loan, that number can become surprisingly important. The good news is that building a healthy credit history does not require earning a huge salary or becoming a financial expert. It is mostly about developing sensible habits early.
So, What Exactly Is a Credit Score?
In simple terms, a credit score is a number that gives lenders an idea of how responsibly you have handled borrowed money in the past. In India, credit scores are generated by credit information companies regulated by the Reserve Bank of India (RBI). There are four licensed credit information companies operating in the country: TransUnion CIBIL, Equifax, Experian and CRIF High Mark.
TransUnion CIBIL is the oldest and perhaps the most widely recognised, which is why people often use the word “CIBIL” when talking about their credit score. Equifax and Experian are global credit information companies that provide credit reports and scores, while CRIF High Mark is an RBI-approved bureau that covers both consumer and commercial lending in India.
A CIBIL score generally ranges from 300 to 900, with a higher score usually indicating a stronger credit history. Lenders may consider this score along with your income, existing debts, repayment history and other financial information when deciding whether to approve a loan or credit card and what terms to offer. Your credit history can include things such as credit cards and loans, as well as whether you have consistently made your repayments on time.
This is where being 22 actually matters. If you have never borrowed money before, you may not have much of a credit history at all. That does not mean you have a bad score. It simply means there may not be enough information for lenders to assess your borrowing behaviour. And that distinction is important because being financially responsible and having a long credit history are not necessarily the same thing. For someone in their early twenties, having little or no credit history can simply mean that you are at the beginning of your financial journey.
Understanding Your Credit Score and its Range
In India, the credit score can range between 300-900, but these numbers become more useful when you understand what each score stands for. A credit score of 800-900 can be considered the excellent category, which indicates low risk and qualifies for the best interest rates and fastest approvals. A score of 760-800 falls under the ‘very good’ category, indicating strong creditworthiness and smooth loan and card processing. People with a score of 701-760 fall under the ‘good’ category, which is the most common for people who pay on time with no delays and meet standard approval terms.
A score between 601–700 falls into the average or fair range, where borrowers may face stricter terms or higher interest rates. Scores between 300–600 are considered poor and can make accessing credit more difficult. If your report shows NH or NA, it generally means you are new to credit, and there is not enough information to generate a score. For someone in their early twenties, seeing NH or NA is not necessarily a bad thing. It simply means you have not built enough credit history yet.
Why Should You Care About It So Early?
You might be thinking, “I don't have a loan, so why should I worry about my credit score?”
Because financial decisions tend to arrive earlier than we expect. Maybe you want to buy a laptop or phone on EMI. Perhaps you need an education loan for further studies, a credit card for travel or an auto loan a few years from now. When that happens, lenders will look at your financial profile rather than simply asking whether you are a good person who pays their bills. A strong credit history can make borrowing easier, although approval is never guaranteed and lenders use several factors to make their decisions.
It can also affect the terms you are offered. A stronger credit profile may help you access more favourable borrowing conditions, while a weak history can make getting credit more difficult or expensive. That is why your early twenties can actually be a useful time to start paying attention. You are not trying to become obsessed with a number; you are giving yourself time to build a financial track record.
Your First Credit Card Is Not Free Money
This is probably the biggest trap for young adults. Getting your first credit card can feel like receiving extra money every month. It isn't. A credit card is a form of borrowing, and whatever you spend eventually has to be repaid. If you consistently pay your bills on time and manage your credit responsibly, the account can become part of your credit history. But carrying large unpaid balances, missing payments, or repeatedly borrowing more than you can comfortably repay can create problems. The simplest rule is one that sounds almost boring: only borrow what you can realistically repay.
What Shapes Your Credit Score?
Your credit score is based on information reported by banks and financial institutions, including your repayment behaviour and existing credit accounts. Payment history is one of the most important factors, so consistently paying EMIs and credit card bills on time matters.
Another factor is your credit utilisation ratio, which refers to how much of your available credit you are using. For example, if your credit card has a ₹1 lakh limit and you regularly use ₹80,000 of it, lenders may see that as relatively high utilisation. Keeping usage comfortably below the limit, often with 30% used as a general guideline, can help maintain a healthier profile.
Your credit mix and length of credit history also matter. Having different types of credit and maintaining older accounts responsibly can contribute to your profile, although you should never take a loan simply to create a particular “mix”.
Finally, applying for several credit cards or loans within a short period can result in multiple hard inquiries on your credit report. Too many applications in a short period may make lenders wonder whether you are relying heavily on borrowed money, so spacing out applications is generally sensible.
What Actually Helps Build a Good Credit History?
You do not need to take out a massive loan just to build a credit score. In fact, borrowing money you do not need simply for the sake of creating a credit history is a poor financial decision.
If you have a credit card, paying the bill on time is one of the most important habits you can develop. It is also worth keeping an eye on how much of your available credit you are using rather than regularly pushing your card close to its limit. Another useful habit is checking your credit report periodically. Mistakes can happen, and spotting an unfamiliar account or incorrect information early gives you a chance to raise a dispute.
It is also good to be careful about applying for lots of credit products in a short period. Each application may involve a lender checking your credit profile, and multiple applications can sometimes signal that you are actively seeking credit. Most importantly, do not treat your credit score as a measure of your overall financial worth. Keeping your credit utilisation under control rather than regularly using most of your available limit can also be a great step. If possible, paying down your balance before the statement is generated can help keep the reported utilisation lower.
Finally, avoid applying for several credit cards or loans just because they are being offered to you. Every new application should have a reason behind it, and spacing out applications can help you avoid creating a pattern of frequent credit-seeking. Most importantly, don't borrow simply because you want to improve your score. A good credit score is a result of responsible borrowing, not a reason to borrow more. A high score does not mean you are financially successful, and a limited credit history does not mean you are irresponsible.
The Habits You Build at 22 Can Follow You for Years
There is something useful about learning about credit before you desperately need it.
At 22, you have time to make small mistakes, learn how borrowing works and develop habits that can serve you later. You can learn the difference between a credit card and a debit card, understand what interest actually costs, read the terms before signing up for an EMI and stop thinking of every available credit limit as money you can spend.
You can also learn to ask a very simple question before borrowing: “Do I actually need this, and can I comfortably repay it?” That question may be more valuable than any three-digit score.
Your credit score is not something you need to check every morning or panic about whenever it changes. Think of it more like a financial report card that gradually reflects how you have handled credit. At 22, you may not be planning to buy a house tomorrow. You may not even know what city you will be living in five years from now. But your future self might want a loan, a car, a home or simply the freedom to access credit without unnecessary complications.
Building good financial habits now does not guarantee that everything will go smoothly later, but it can certainly put you in a better position when those bigger financial decisions arrive. And that is probably the real reason a 22-year-old should care about a credit score: not because the number matters today, but because the habits behind it might matter for years to come.